A gym business loan in St. Charles, MO can take two forms: equipment financing for racks, turf lanes and cardio, where the machines secure the debt, and a term loan for movable furnishings for a bigger lease; fixed room work is excluded. This article prices both with invented figures and shows how dues and churn figure in a request.
Invented figures for a strength package and movable studio furnishings, a dues-and-churn check, and St. Charles County, MO counts for fitness and recreational sports centers (NAICS 713940).
Racks, turf lanes and cardio for St. Charles, MO gyms
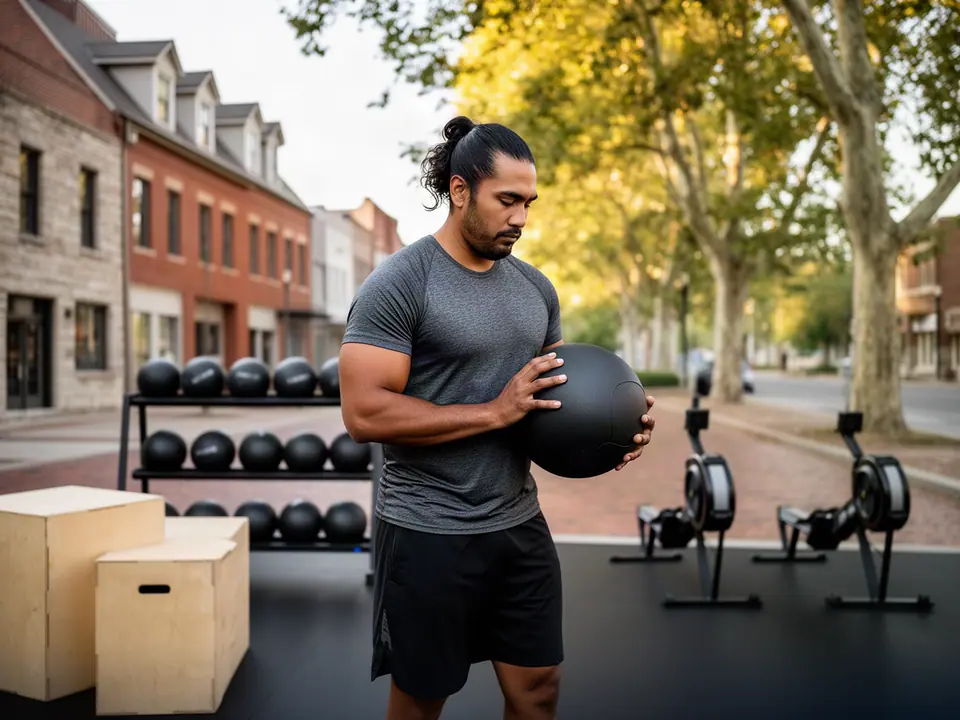
Strength equipment is a good fit for equipment financing because each piece has a model, a serial number and a resale market. The financing is secured by the equipment itself, so the term is set around how long the racks, plates and treadmills stay in service. Turf lanes and movable exercise mats can have supplier prices and model details; fixed flooring is excluded.
County Business Patterns counted 65 fitness and recreational sports centers (NAICS 713940) with paid employees in St. Charles County, MO in 2023, with 1,084 paid employees in the mid-March pay period and an annual payroll of $15.3 million. That is about 17 employees per location, our arithmetic. Fewer than five people worked at 30 of those 65 gyms and studios (46.2%). ZIP Code Business Patterns put 8 such centers at a ZIP 63301 address in 2023.
Illustration only, invented figures. A gym prices a strength package: 6 half racks at $2,450, 6 bar-and-plate sets at $1,180, a 40-foot roll of removable turf priced at $5,600 and 4 commercial treadmills at $4,900, for $46,980 in this example. Spread over 48 months at 10.25% a year, the package costs $1,197.18 each month in this example, and the 48 payments total $57,464.64.
A bigger lease and the movable furnishings it needs
Moving into a larger space is a different kind of cost. A larger room can use movable exercise mats, freestanding lockers and mirrors, and self-contained sound and air-quality equipment. A partner can review a term loan for those supplier-quoted items; fixed flooring, shower plumbing and air handling are excluded. Funding here covers a leased space; buying the building is not part of it.
The lease itself shapes the request. A landlord may contribute a tenant improvement allowance, offer months of reduced rent while the work is done, or ask for a larger security deposit. Each changes the amount the gym has to fund. The signed letter of intent or lease draft, the supplier quote and a timeline to opening are the papers a reviewer can read the movable-equipment plan from; fixed room work is excluded.
Illustration only, invented figures. A supplier quotes $118,000 for movable studio equipment and freestanding furnishings, and the landlord pays a $40,000 allowance for those items, which leaves $78,000 in this example; fixed room work is excluded. On a 72-month term loan at 11% a year, that balance carries a payment of $1,484.66 in this example, and the 72 payments come to $106,895.52 in all.
Membership revenue and churn in a loan request
Dues are the revenue a gym request rests on, and churn is what a reviewer reads them against. A month of strong sign-ups says less than twelve months showing how many members stay. A membership system can export active members, new joins, cancellations, freezes and failed card charges by month, and that export lines up with the deposits on the bank statements.
Illustration only, invented figures. The billing run collects $24,320 in this example from 380 members whose dues average $64. In this example a monthly churn of 3.5% means about 13.3 members leave each month, so the gym needs 14 new members a month just to hold its billing level. In this example both payments from the sections above together come to $2,681.84 a month, or 11.0% of that billing, our arithmetic.
Personal training, class packs and retail sales belong on separate lines from dues. They count as revenue, but they move differently, and a reviewer can weigh steady dues more than a month of package sales. A business line of credit can cover the weeks between a dues run and a payroll that falls before it.
Equipment loan or term loan for a St. Charles County, MO gym
The two products answer different questions. One asks what the equipment is worth and how long it will last. The other asks whether the business can carry a fixed payment for a cost it cannot resell.
| Point | Equipment loan | Term loan |
|---|---|---|
| Pays for | Racks, plates, cardio, turf lanes sold with the package | Movable furnishings, deposit and opening payroll |
| Secured by | The equipment being bought | The business, and any lien or guarantee in the offer |
| Term set by | Service life of the equipment | The amount and what the business can carry |
| What the review reads | Dealer quote, serial numbers, bank statements | Lease, supplier quote and dues records |
A gym moving to a bigger lease can use both: equipment financing for the new strength floor and a term loan for movable furnishings, sized together against the dues it expects to keep; fixed room work is excluded. The gyms and fitness studios page covers reformer studios, locker rooms and buying an existing gym.
By Clovershire Credit · Updated